Debt Hacker · Founder and inventor, not yet launched · 2024 to now
Built for the other side of the table
For people who owe more on their credit cards than they can pay down fast
Card issuers decide how far above the prime rate to price a card, and in 2024 that markup hit a record. I invented Debt Hacker for the people paying it, who owe more on their cards than they can pay down fast, to give them a plan for this month built on their own cards, explained in plain English.
With help from Patrick Hrabos
The problem
About half
of credit card accounts in use carry a balance from month to month, at rates that average about 22 percent.
The short version
The trap
Almost 10 years
That’s how long the CFPB’s example, $2,000 on a card at 29 percent, takes to clear at the minimum, with more than $3,000 going to interest.
The plan
Your month, card by card
In the version we’ve built, not yet launched, Debt Hacker turns your own cards, bills and income into a plan for this month: AI reads the statements, you check and correct the card details it found, and the math runs in code that can be checked.
What a simulation suggested
Simulated: about 4 in 10 → 7 in 10
I had AI agents build a simulation of 3,000 households over ten years. Of those who owed $3,000 or more they couldn’t clear within a year, about 4 in 10 got out of debt on their own and about 7 in 10 with the full approach, though most of the gain came from parts still to be built.
Late at night, card in hand
It’s late, there’s a card in your hand, and the math in your head goes like this: you paid every card last month, and the balances barely moved. Each statement tells you how long that one card will take at the minimum. None of them tells you which of your five cards should get the next dollar, or that most of the minimum you just paid went to interest.
That’s where a lot of people live. About half of card accounts in use carry a balance from month to month, at rates that average about 22 percent. The CFPB’s own example is a $2,000 balance at 29 percent: paid at the minimum, it takes almost ten years and more than $3,000 in interest to clear.
What it does to people
Research links that kind of debt to higher stress, more depression and worse health, and the link is strongest for short-term debt like credit cards, with little sign of it for mortgages. Shame makes it worse, because people who expect to be judged hide their debt and put off getting help, and that makes it harder to pay down.
I’ve watched what years of that cycle do to people’s lives, and I’ve had hard stretches of my own as a founder. That’s what started Debt Hacker: the belief that there’s a better way to look at debt than the one people are usually handed.
Where the usual advice falls short
There’s plenty of advice, from paying the smallest balance first or the highest rate first to cutting up the cards, budgeting every dollar or simply spending less. Each of those gets something right, and none of them told me what I needed: where this month’s money should go, card by card, through good months and lean ones, and how to keep the progress from leaking away.
The usual advice
Each gets something right
- Pay the smallest balance first
- Pay the highest rate first
- Cut up the cards
- Budget every dollar
- Spend less
What I needed
A plan for my actual month
- Where this month’s money should go, card by card
- A plan that holds through good months and lean ones
- A way to keep the progress from leaking away
Who the math works for
At the biggest issuers in 2022, people who carried a balance paid 94 percent of the interest and fees, while people who paid in full collected 73 percent of the rewards. Whatever got someone into debt, I wanted them to have the kind of math the lender already has. So I went looking for the holes in the system, starting with which card a regular bill goes on and when a payment lands compared with when charges post.
At the biggest card issuers, 2022
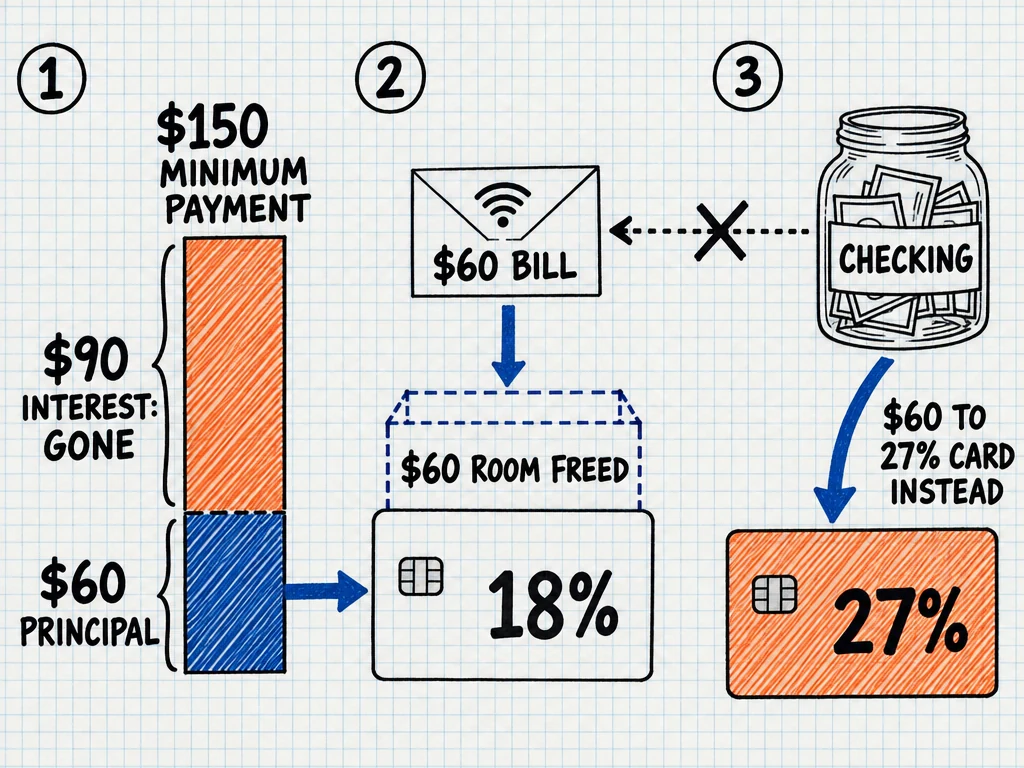
In round numbers, a $6,000 balance at 18 percent has a $150 minimum (1 percent of the balance plus interest): $90 of interest and $60 of principal, which frees $60 of room on the card. Once that payment posts, put a $60 bill there instead of paying it from checking, and send the $60 from checking to the 27 percent card. Your total debt ends the month where it would have anyway, but $60 of it now costs 18 percent instead of 27: about 45 cents saved the first month, growing as the move repeats. Use a bill that charges no fee for paying by card.
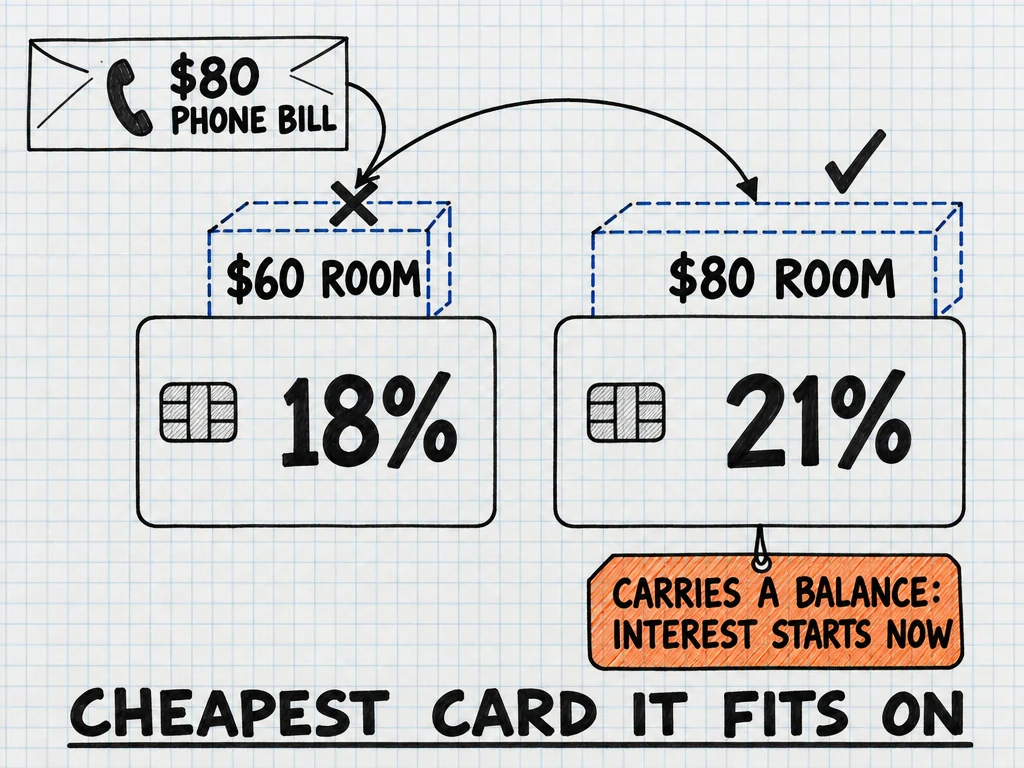
Each card’s room is the principal its last minimum payment paid off, so a bill that fits leaves that card’s balance where it started. Cards are tried from the lowest rate up, and a bill goes on the first card with room for all of it, never split. The $80 phone bill doesn’t fit the 18 percent card’s $60, so it goes on the 21 percent card. Like every card with room, it carries a balance, so there’s no grace period, and the bill starts costing 21 percent right away.
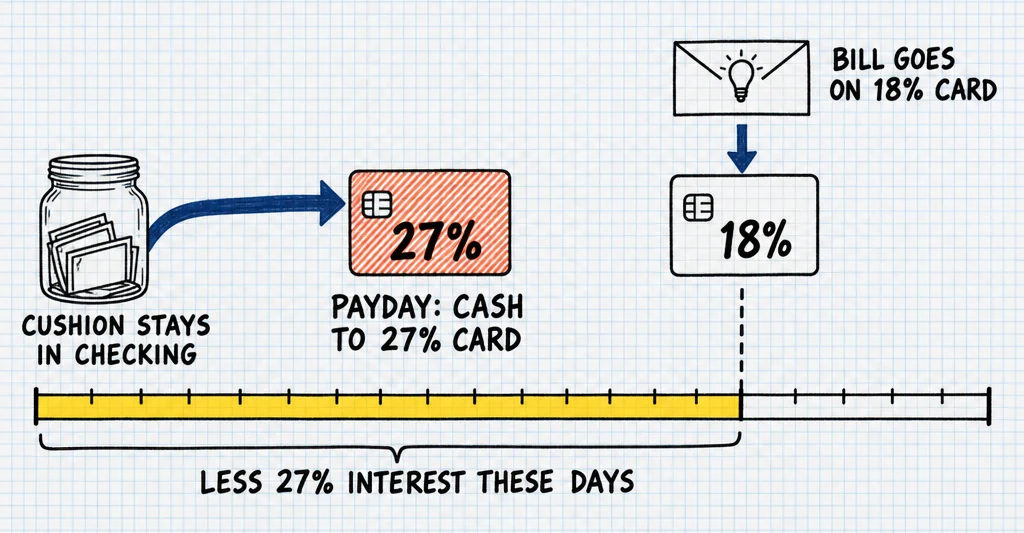
Compared with sending the bill’s cash to the 27 percent card when the bill posts, sending it on payday means fewer days of 27 percent interest. Either way the bill goes on the cheapest card it fits on and costs that card’s rate from the day it posts. The saving is small, and it only works when your income covers your bills, you keep a cushion in checking, and you hold back the cash for every card’s minimum payment and for any bill a card can’t take, like rent.
What we’ve built so far
I worked out the method in a spreadsheet in 2024 and used it for months. In early 2025 I built a working first model in about three weeks, with AI writing most of the code. With help from Patrick Hrabos, it has grown into an engine that turns a person’s cards, bills and income into one plan for the month. In the version that’s built and not yet launched, AI reads your statements, and you check and correct the card details it found before anything is calculated. The plan itself is calculated in plain code that can be checked, and AI reads the paperwork and helps explain the plan.
If more money goes out each month than comes in, it refuses to make a plan and says so. It doesn’t ask for a bank login.
How a plan gets made, in the version we’ve built
- Your statements
- AI reads them
- You check the card details
- Code that can be checked does the math
- One plan for this month
If more goes out each month than comes in, it refuses to make a plan and says so.
What the simulation changed
To test whether my approach would work for people, I had AI agents research published US data and build a simulation of three thousand households over ten years, with some inputs still assumptions to replace. For the households carrying $3,000 or more that they couldn’t pay off within a year, the full approach raised the share who got out of debt from about four in ten to about seven in ten, and most of that gain came from parts I haven’t built yet.
Choosing between payoff orders made almost no difference. Having a plan for which card gets the extra money helped, but in interest saved it was worth less than half as much as guarding against re-borrowing, which the model assumed would cut it in half. Cashflow reclamation, the foundation of Debt Hacker’s plan, saved little on average and stretched the payoff a little, but for about 15 percent of those households it saved more interest than anything else in the approach, a median of about $3,600.
In the simulation, what mattered most was whether people kept going and whether new spending undid their extra payments. Research found that people using a debt app cut their debt by only 25 to 30 cents for each dollar they planned to pay down: most made their payments, but new spending usually offset them, and I built that into the model. Those results point toward guarding against re-borrowing, staying with people month to month, helping people ask for a lower rate, and a community of people working through the same thing. In one field experiment, people who feared being judged felt better after a debt course taken with others than after the same course taken privately online, and the connections they made there kept them motivated to pay down debt. All of these numbers stay provisional until real people use Debt Hacker.
In a simulation, who got out of debt
On their own about 4 in 10
With the full approach, mostly not built yet about 7 in 10
What published research found
25 to 30¢
of each dollar people planned to pay down actually came off their debt
In one study of debt-app users, most made their payments, but new spending usually offset them. The simulation used this finding as an input.
Where it is now
Debt Hacker isn’t available yet. I’m starting to talk about it openly now, and it will evolve with what I learn. It brings together what I’ve learned about how cards work, a monthly plan, AI help with the paperwork and, as it grows, people in your corner when the next swipe comes. You can follow it, and tell me what’s been hardest, at debthacker.app.
Where it’s been and where it’s going
- 2024 The method, worked out in a spreadsheet
- Early 2025 A working first model, built in about three weeks
- Since then An engine that turns cards, bills and income into one plan, with help from Patrick Hrabos
- Now Built, not launched. Tested in a 3,000-household simulation that AI agents built
- Next What the simulation points to: guarding against re-borrowing, staying with people month to month, and a community
Next story